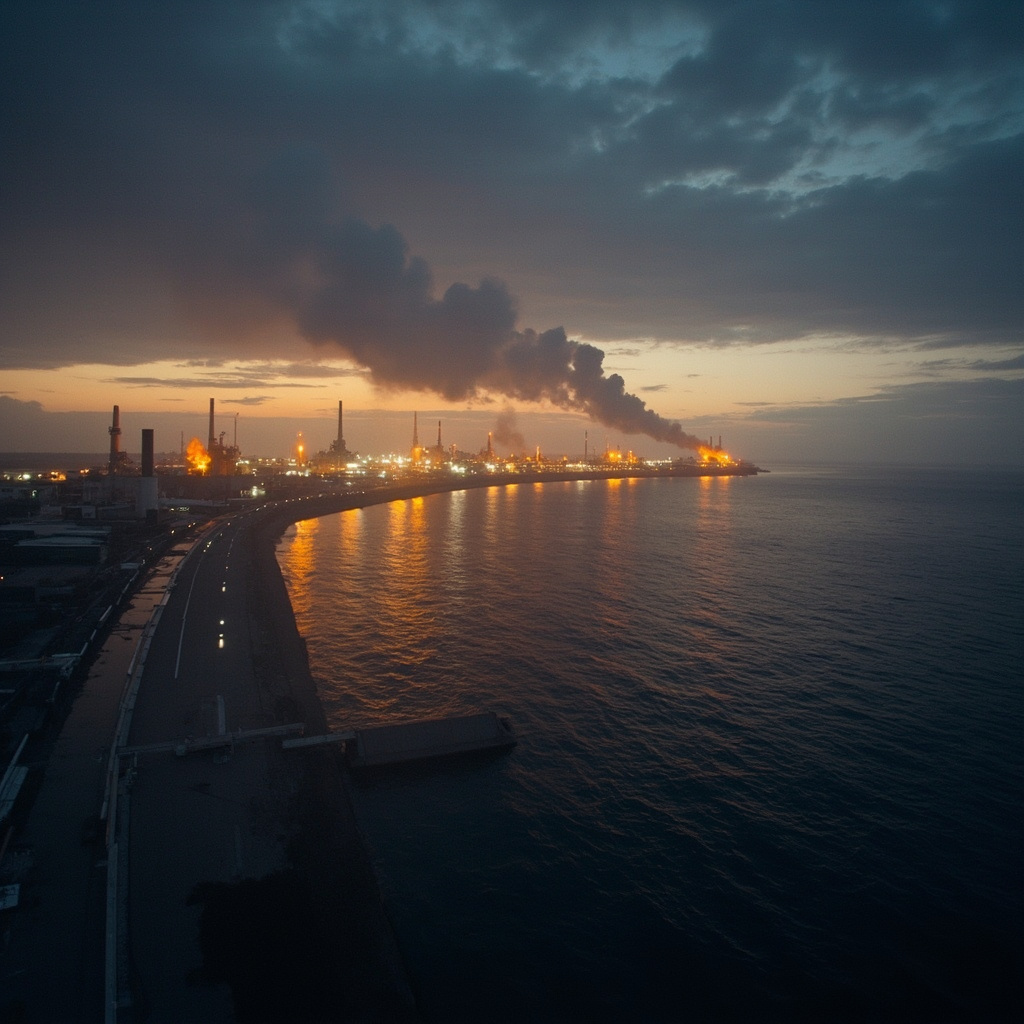
Yesterday this paper wrote about Kharg Island and the market's obsession with a single export node. Today the scope is wider and uglier. The war has moved from supply anxiety to infrastructure combat.
South Pars is not an abstract field on a map. Ras Laffan is not a line item. These are parts of the machinery that keep the Gulf legible to the global economy. Once missiles begin landing around that machinery, the story changes. It becomes less about what traders fear and more about which systems still function.
CNN's day-20 roundup treated the shift with the right emphasis: Iran's retaliation after the South Pars strike hit energy infrastructure across the region, and the White House ruled out an export ban even as prices kept climbing. [1] CNBC's energy and market coverage points in the same direction. South Pars is not merely another target. It is the center of a wider Gulf escalation, and Europe's gas exposure means the consequences travel quickly beyond the battlefield. [2][3]
This Is No Longer a Side Effect
The early energy coverage of the war had a familiar rhythm. Oil rises. Gas follows. Analysts model scenarios. Politicians promise relief. Consumers post pump receipts.
That rhythm still exists. It is just no longer the main event.
The main event is that the war is now moving through the pipes, ports, and shipping lanes that turn regional conflict into global cost. South Pars matters because it is huge. Ras Laffan matters because it is where enormous volumes of LNG actually move. Hormuz matters because it is still the narrow place through which too much of the world's energy must pass.
Once those points are under direct pressure, the market does not need to imagine a worst case in order to react. It only needs to see that the system itself is being handled like a battlefield.
The numbers explain why the repricing has been so violent. South Pars holds the largest natural gas accumulation ever mapped, shared with Qatar's North Field across a maritime boundary that runs directly beneath the fighting. Iran draws the majority of its gas from it. Qatar draws the feedstock for Ras Laffan, one of the two or three largest LNG export complexes on earth and the origin of roughly a fifth of the world's seaborne gas. [2] Europe, having lost Russian pipeline volumes in 2022, rebuilt its winter supply on American shale cargoes and Qatari ones; Asia's buyers signed decades-long contracts into the same terminals. A missile landing near that machinery does not need to hit anything to move prices across three continents by morning. The market saw where it landed.
The Last Time Infrastructure Was the Target
There is a recent rehearsal for this story. In September 2019, drones and cruise missiles knocked out processing at Saudi Arabia's Abqaiq complex and took out roughly 5.7 million barrels per day of capacity — about five percent of world supply — overnight. Brent posted its largest single-day percentage jump on record at the next open. Then the fear unwound almost as fast as it had arrived: spare capacity existed, repairs ran ahead of schedule, and within weeks the episode read as a scare rather than a structural break.
That history is comforting and mostly irrelevant. Abqaiq was a single facility repaired inside a functioning system. This war is striking the system — fields, terminals, refineries, tankers, and the insurance and shipping markets that decide whether cargo can legally and financially move at all. Infrastructure heals slowly. Fear prices instantly. When both are being hit in the same week, the recovery curve of 2019 stops being a precedent and becomes a taunt.
Insurance Is the Invisible Gate
The least visible casualty of the week was announced quietly: marine insurers pulled Gulf war-risk cover, and by mid-March more than 500 tankers were effectively stranded — hulls that could sail but not trade, because no bank finances cargo and no charterer loads crude without coverage. War-risk underwriting works on listed areas and daily rates; when a zone turns hot, premiums can multiply from tens of thousands of dollars per voyage to seven figures, and when cover is withdrawn outright, the voyage simply ceases to exist commercially.
That gate sits upstream of everything visible at the pump. It is why Iranian retaliation against Gulf energy sites matters even where nothing burned, and why the White House ruling out an export ban [1] addresses a lever Washington barely controls. The binding constraint is not American policy. It is the actuarial judgment of London underwriters reading the same strike maps everyone else is.
Qatar Has Stopped Pretending This Is Someone Else's Problem
One of the most revealing details in CNN's account is not a price figure. It is that Qatar ordered Iran's military and security attaches to leave within 24 hours after the damage at Ras Laffan. [1]
That is the language of a Gulf state signaling that the old posture of balancing, hedging, and absorbing is getting harder to maintain. Energy war puts everyone in the neighborhood on a clock. So does the simple fact that infrastructure cannot be symbolically damaged. It is either functioning or it is not. Cargo either moves or it does not. Insurance either remains on offer or it does not.
Doha's dilemma is the region's in miniature. Qatar hosts the largest American air base in the Middle East and sells the LNG Europe heats with; it cannot choose between Washington and Tehran without choosing against itself. Expelling Iranian diplomats within a day of the Ras Laffan damage is what hedging looks like when the hedge itself is burning — a gesture aimed less at punishing Tehran than at showing Washington and Doha's own customers that neutrality has limits.
Yesterday's story on Iran's strikes across Gulf sites captured the opening form of this escalation. Today's delta is that the region's economic nervous system is now the contested space itself.
The Hidden Tax Arrives Before the Official One
The public sees pump prices first. The system feels insurance, rerouting, risk premia, delays, and hedging costs before that. CNBC's market coverage on Thursday put the larger point plainly: investors are now repricing the war as an inflation problem with growth consequences, not just as another geopolitical headline. [4]
That is how infrastructure war works. It taxes the world before any government writes the tax down. A tanker route gets longer. A policy option disappears. A refinery hit becomes a spread move. A central bank rethinks its assumptions. Then an ordinary person pays more for fuel and wonders why every explanation sounds one step behind the bill.
The chain is traceable at each link. Supertanker day rates multiply as owners demand danger money or refuse Gulf calls outright; cargo that once moved through the Strait begins pricing in the long way around, adding weeks and millions of dollars per voyage. European gas futures follow every Ras Laffan headline because winter storage cannot be rebuilt mid-season. Bond desks at the Bank of England and the ECB now model war-driven inflation against war-slowed growth — the ugliest combination a rate-setter can face, stagnation imported through an energy bill [4] — while Washington insists the problem is temporary and traders mark it permanent.
The White House may have taken export restrictions off the table, but that mostly tells you what it is unwilling to do. It does not solve the harder problem, which is that the war is now touching the mechanisms that set the price of movement itself.
The Gulf can survive a great deal of rhetoric. Its infrastructure is less forgiving.
-- YOSEF STERN, Jerusalem